
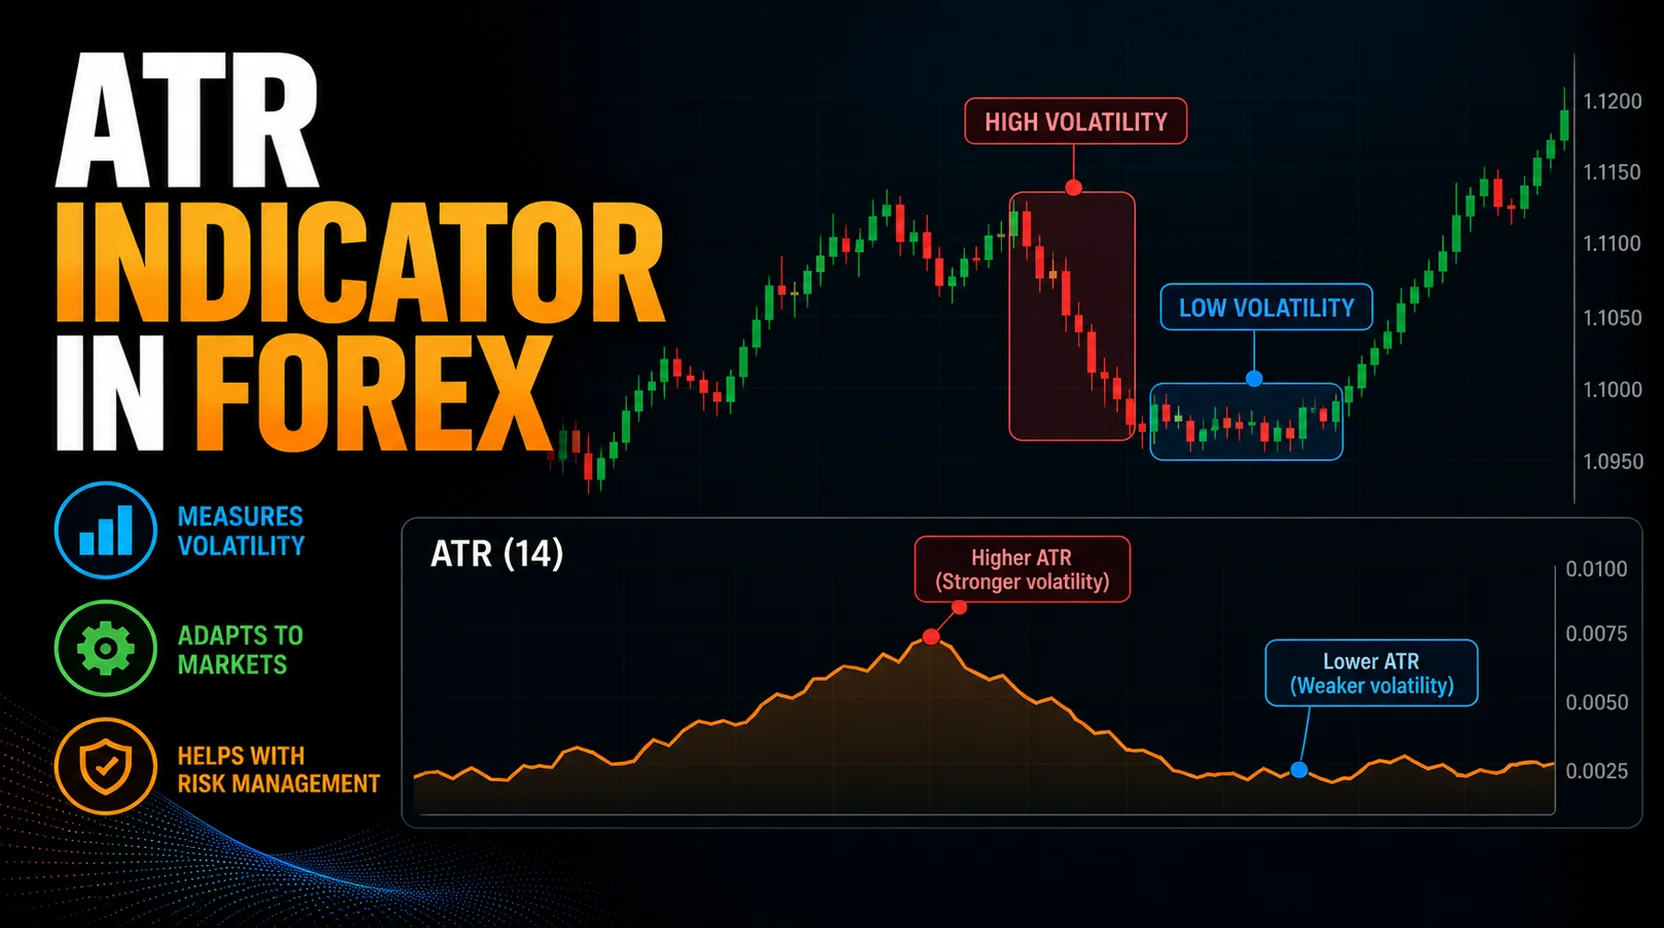
What Is ATR in Forex?
ATR stands for Average True Range. Developed by J. Welles Wilder, it estimates the typical size of recent price movements by smoothing True Range over a chosen number of bars. Traders use it to compare volatility across periods on the same chart.
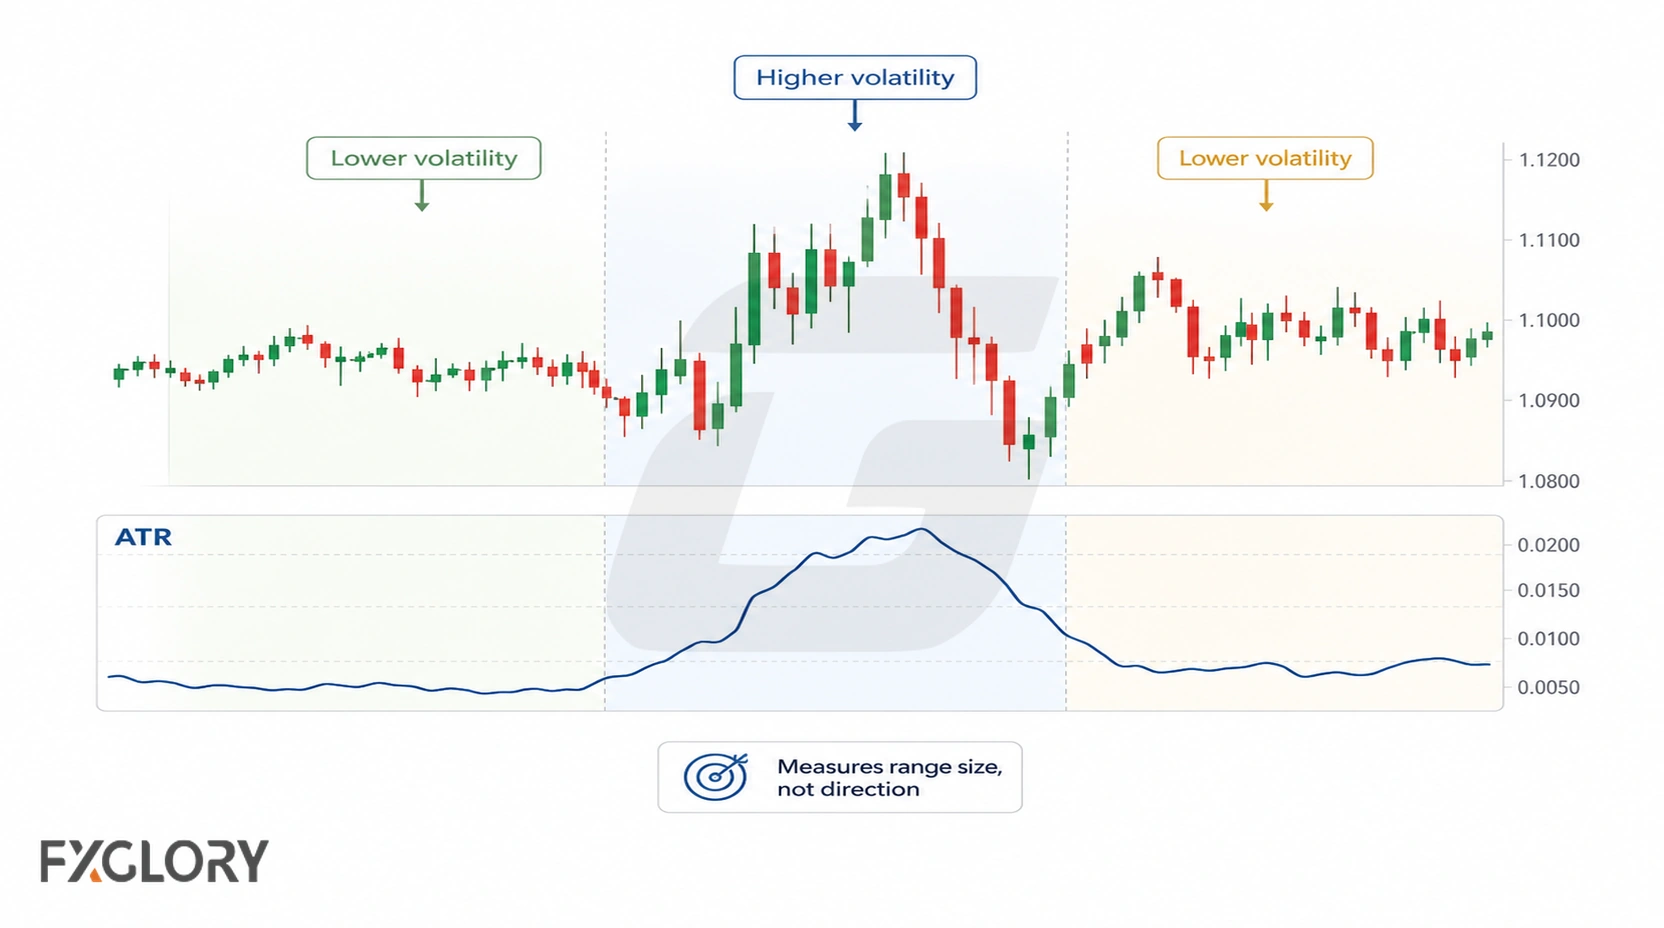
ATR rises as recent ranges expand and falls as they contract. It measures movement size rather than bullish or bearish direction; a volatile market can rise, fall or move erratically.
For a separate measure of trend strength, see ADX in forex.
How the ATR Forex Indicator Works
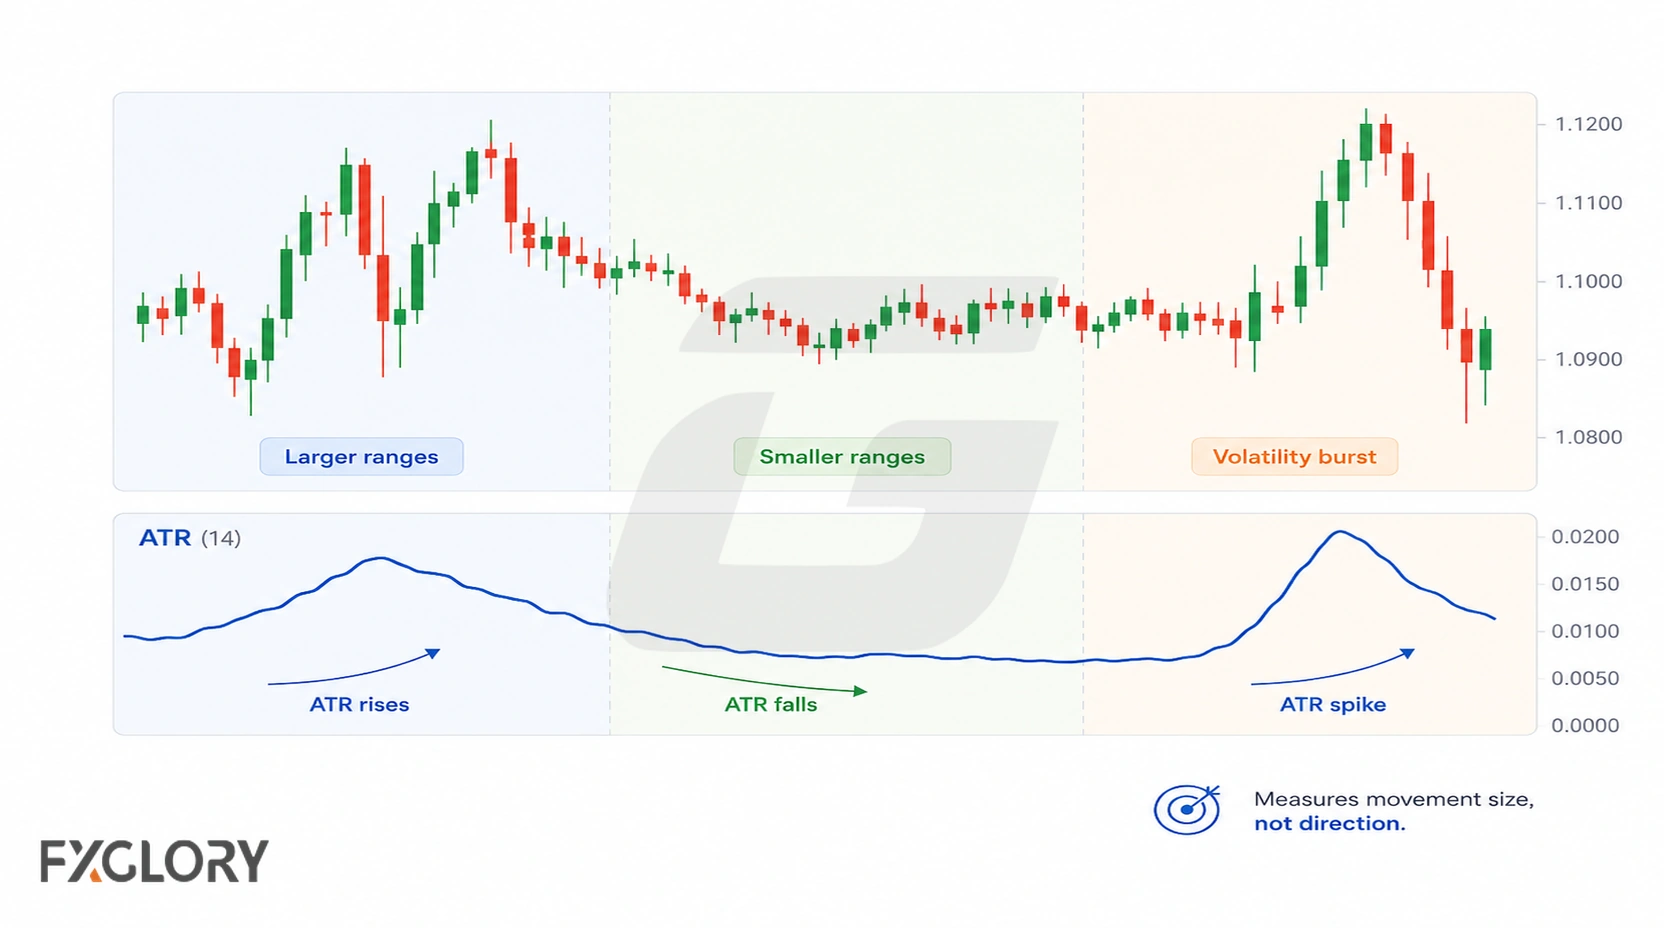
ATR is usually plotted as a line below price. Rising readings indicate that larger True Ranges are entering its average; falling readings indicate that smaller ranges are gradually replacing larger ones. A sudden spike can remain influential after the triggering bar because smoothing takes time to adjust.
- Rising ATR: Recent movement is expanding.
- Falling ATR: Recent movement is contracting.
- Stable ATR: Range size has changed relatively little over the selected lookback.
- Sharp spike: One or more unusually large bars have increased the measure; inspect news and price action before interpreting the move.
What Is True Range?
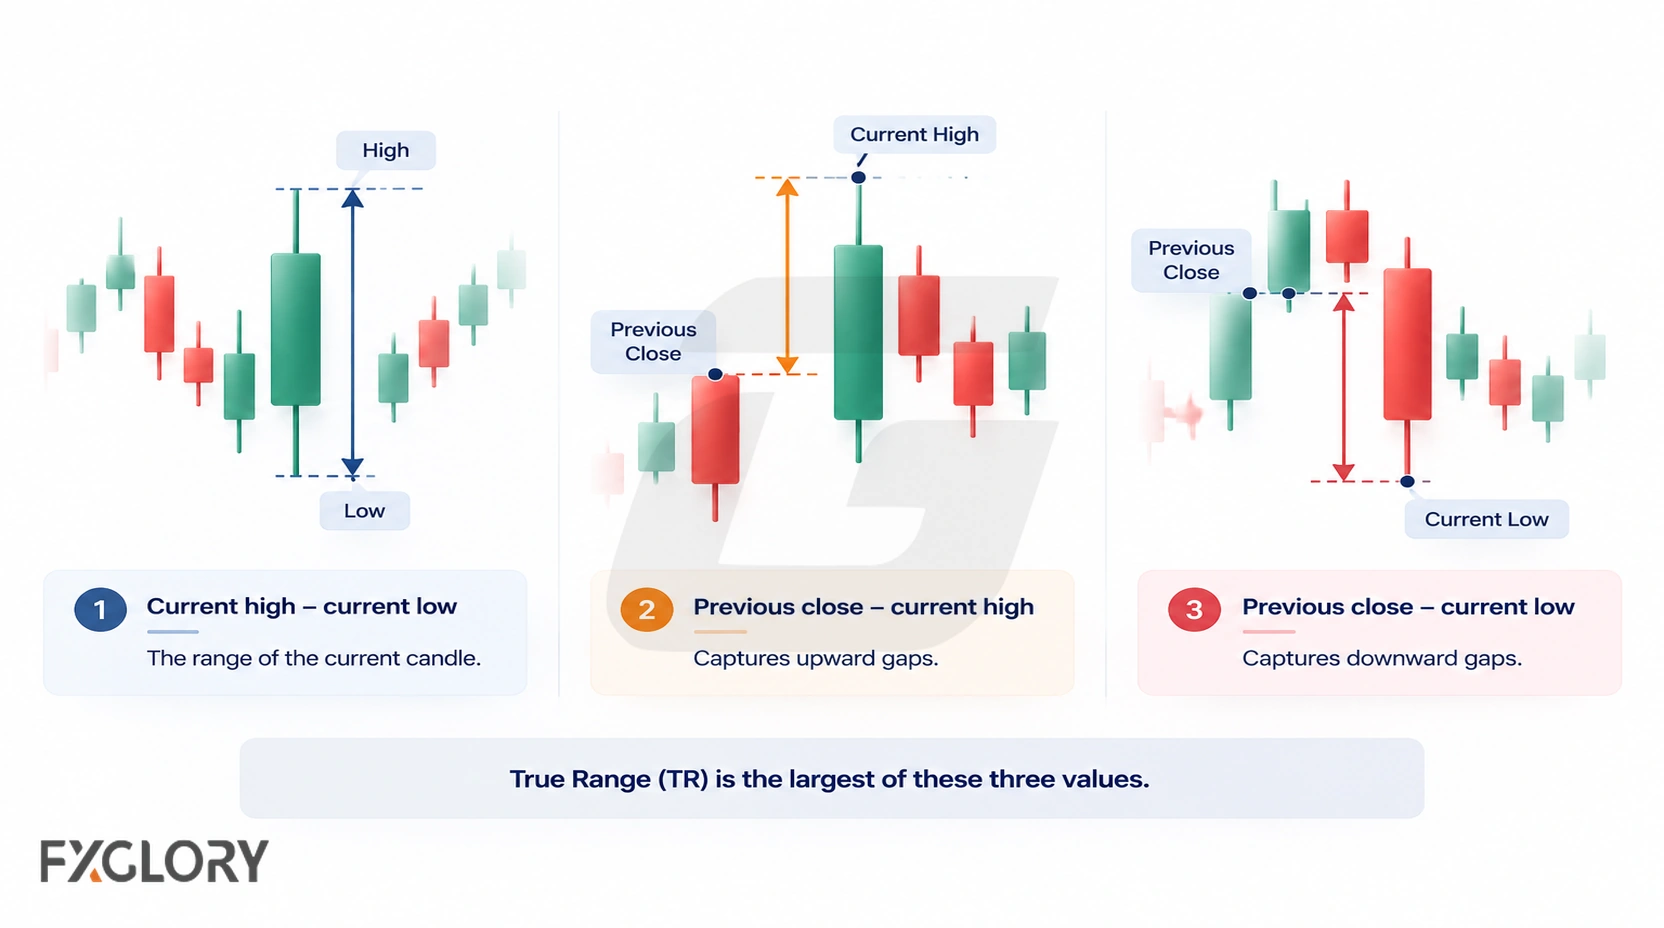
| True Range check | What it captures | Why it matters |
|---|---|---|
| Current high minus current low | Normal candle range | Shows the visible high-to-low movement inside the candle |
| Absolute distance between current high and previous close | Upward jump from the previous close | Captures movement that may not appear in the candle body alone |
| Absolute distance between current low and previous close | Downward drop from the previous close | Captures downward gaps or sharp movement from the prior close |
For each bar, True Range (TR) is the greatest of high minus low, the absolute difference between high and the previous close, and the absolute difference between low and the previous close. This includes gaps that the visible high-low range alone might miss.
ATR Formula and Wilder Smoothing
TR = max(High − Low, |High − Previous Close|, |Low − Previous Close|)
With the conventional Wilder method, the first ATR is initialized as the arithmetic mean of the first N True Range observations. Subsequent values use:
ATR(current) = [ATR(previous) × (N − 1) + TR(current)] / N
At N = 14, the previous ATR has a weight of 13/14 and the latest True Range has a weight of 1/14. Some platforms offer a simple moving average or other smoothing method, so equal lookbacks need not produce identical values.
ATR is expressed in the instrument’s price units. For EUR/USD, an ATR of 0.0012 equals 12 pips when one pip is 0.0001.
High ATR vs Low ATR in Forex
High and low describe ATR relative to an appropriate baseline, usually its own history on the same instrument and timeframe. A reading of 12 pips may be elevated after a quiet period averaging 6 pips, but subdued after a period averaging 20 pips.
- Elevated ATR: Average recent ranges are larger than the comparison baseline; inspect whether this reflects a trend, news shock or choppy volatility.
- Low ATR: Recent ranges are relatively small; the condition can persist without a breakout.
- ATR spike: Check whether a single exceptional bar is temporarily lifting the smoothed reading.
ATR Measures Volatility, Not Direction
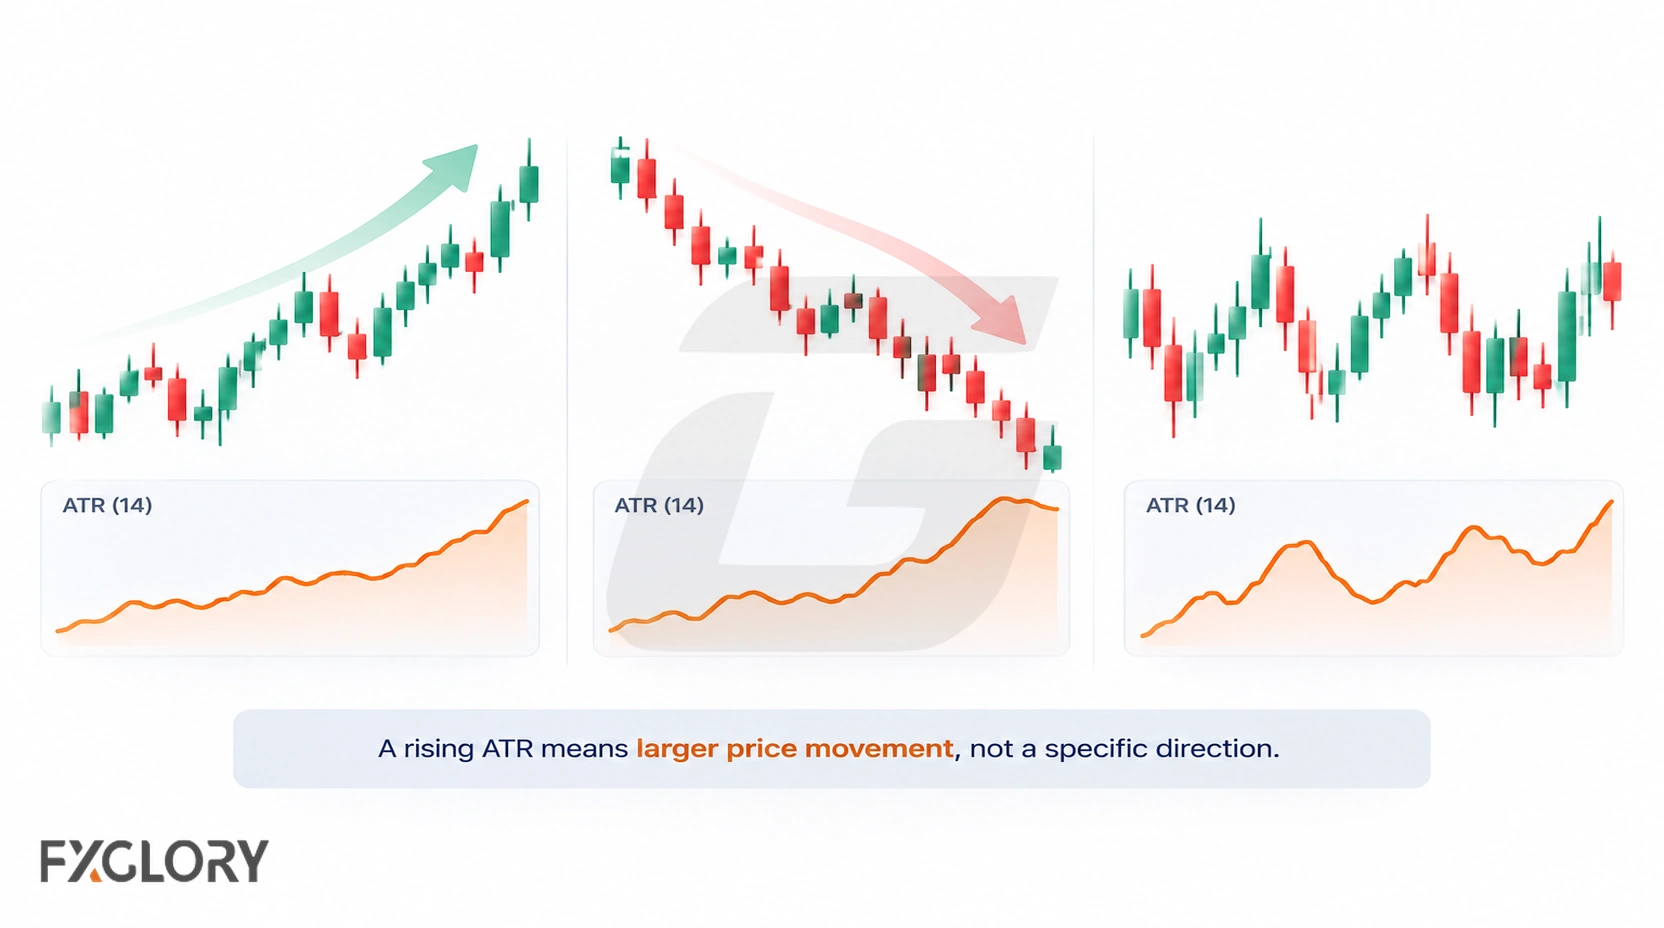
The illustrations show ATR increasing in an uptrend, a downtrend and erratic sideways movement. A directional conclusion therefore requires separate evidence from price structure or another directional method. Use ATR to gauge how large those moves have been, not which way the next move will go.
Why ATR Values Depend on Pair and Timeframe
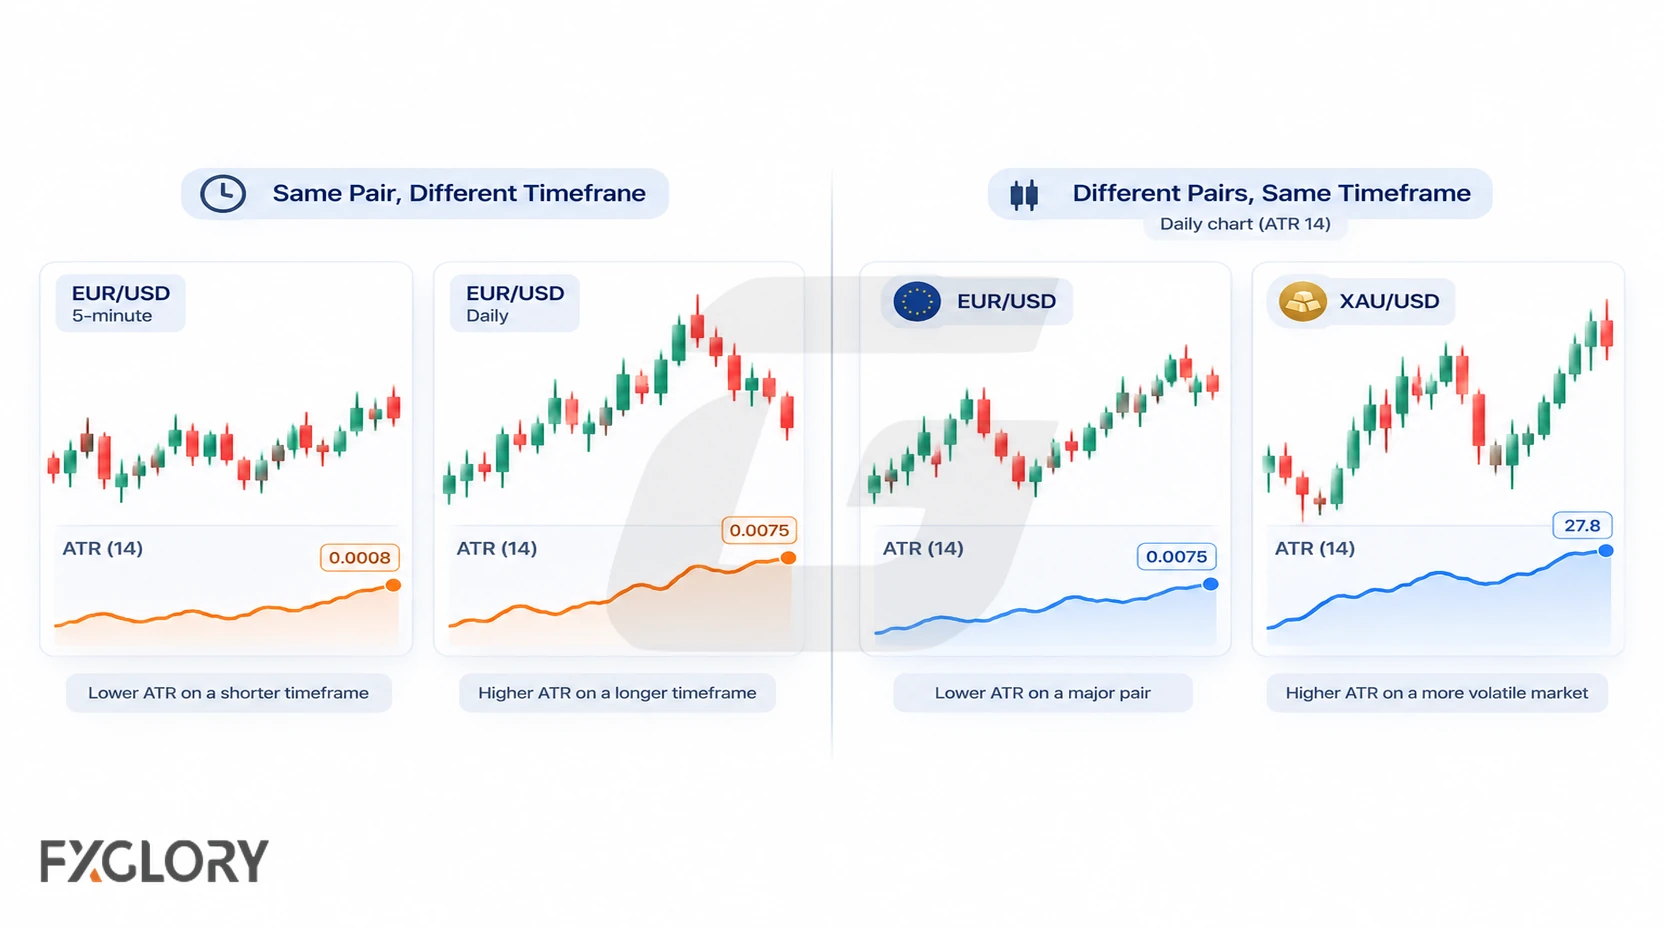
A 14-period ATR on a 5-minute chart summarizes movement across 5-minute bars, while the same lookback on a daily chart summarizes daily bars. Raw values also depend on the instrument’s quotation units: a gold price move, a forex pip and a cryptocurrency dollar move are not directly interchangeable.
Compare an instrument’s ATR with its own recent history using a consistent timeframe, data source and smoothing method. If comparing volatility across different prices or instruments, normalize the measure where appropriate rather than comparing unadjusted numbers.
ATR Settings in Forex
Fourteen periods is a common ATR lookback. Shorter settings adapt more quickly to new range conditions but fluctuate more; longer settings smooth isolated spikes but react more slowly. Choose the lookback according to the decision being studied, and keep it fixed when evaluating examples to avoid overfitting.
The smoothing method matters as well as the period: a 14-period Wilder ATR can differ from a 14-period simple average of True Range.
ATR vs ADX, Bollinger Bands, and Other Tools
ATR measures smoothed True Range in price units; ADX gauges trend strength; Bollinger Bands use dispersion around a moving average to form price bands. They answer different questions and should not be treated as independent confirmation simply because several indicators move at once.
For a broader comparison, see forex volatility indicators.
ATR and Risk Distance in Forex
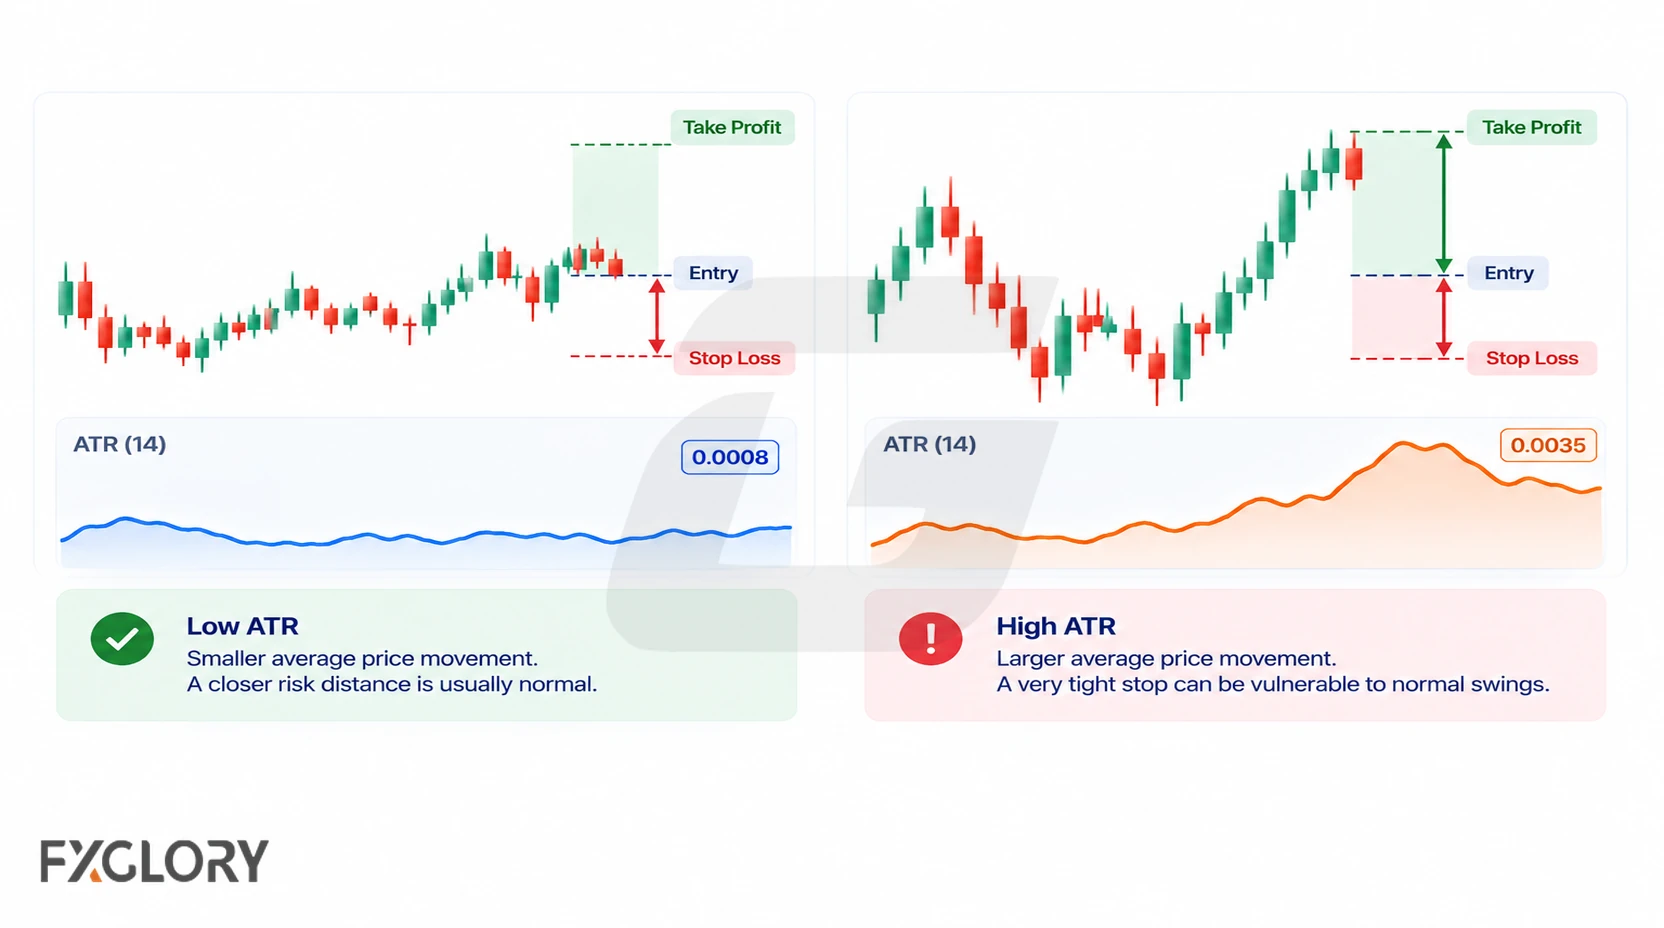
ATR helps assess whether a proposed stop or target distance is small or large relative to recent price movement. For example, a stop 5 pips away sits inside a recent 15-pip ATR, but that comparison alone cannot tell whether the stop is correctly placed.
Set invalidation according to the trade setup and price structure; then calculate position size from the chosen stop distance, instrument pip value and account risk limit. Larger ATR does not automatically require a wider stop. For rule-based volatility stop methods, see the ATR stop-loss strategy guide.
How to Use ATR in Forex
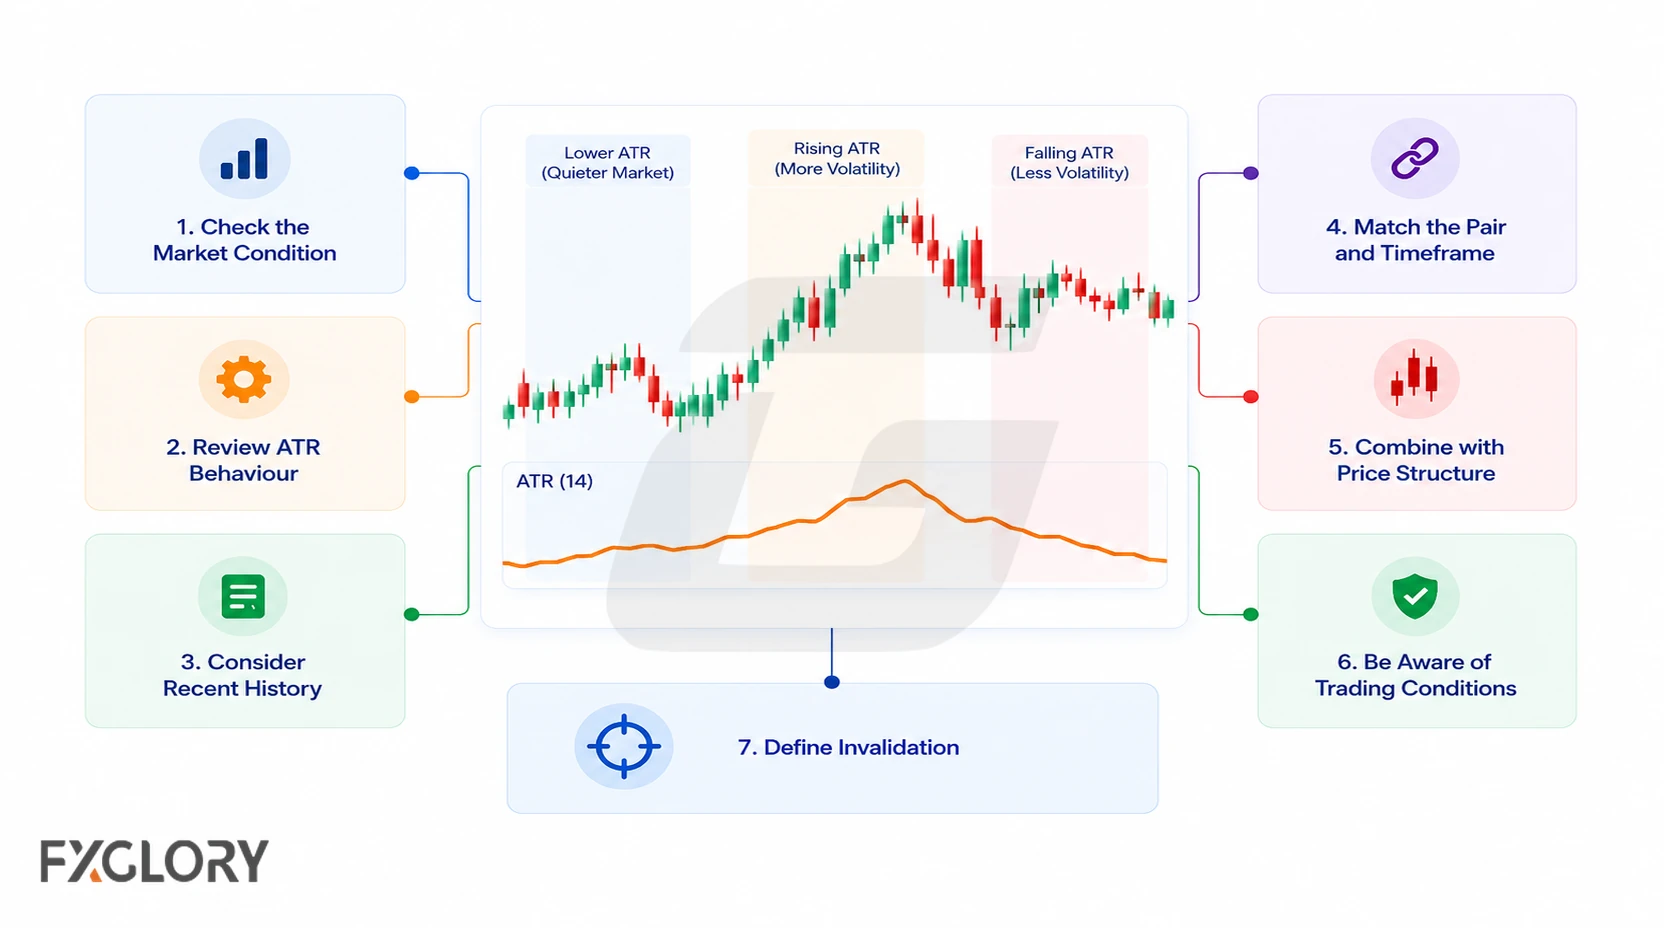
- Identify the question: Are you evaluating compression, expansion or the size of recent swings?
- Compare consistently: Read current ATR against recent values on the same instrument, timeframe and setting.
- Locate price: Check trend, support and resistance, and whether movement is orderly or choppy.
- Check trading conditions: Review current spreads, relevant news and liquidity when using volatility information in a plan.
- Separate measurement from the trade: Use price invalidation and a defined risk limit for trading decisions.
For chart context, see support and resistance and market structure.
ATR Chart-Reading Examples
These are hypothetical exercises, not current ATR observations or tested trading results.
- GBP/USD chart: If price breaks above a range as ATR rises, compare the expansion with price structure and watch for a failed breakout; ATR alone does not establish follow-through.
- Gold chart: If ATR spikes after news, compare the new range with earlier bars and account for execution costs before interpreting a proposed risk distance.
Common ATR Interpretation Errors
- Direction from volatility: Mistaking large ranges for an established trend.
- Breakout from compression: Assuming low ATR guarantees imminent expansion.
- Cross-market comparisons: Treating different price units and timeframes as equivalent.
- Event distortion: Treating a news-driven spike as representative of ordinary sessions.
- Overfitted settings: Changing periods or multipliers to make past charts look convincing.
How to Evaluate ATR on Historical Charts
Assess ATR in a defined market and timeframe rather than choosing only favorable examples. Record the lookback, smoothing method, source, current reading relative to recent history, and market condition (trend, range, breakout or news-driven volatility). Include periods where ATR did not help distinguish useful conditions.
If evaluating an ATR-based trading rule, define entries, exits, stop logic, costs and risk before testing. Do not infer a profitable strategy from an ATR pattern alone.